 InfoSearched
Lease hacking turns the monthly payment fight into a spreadsheet war, and Scott Smith just handed viewers the formulas.
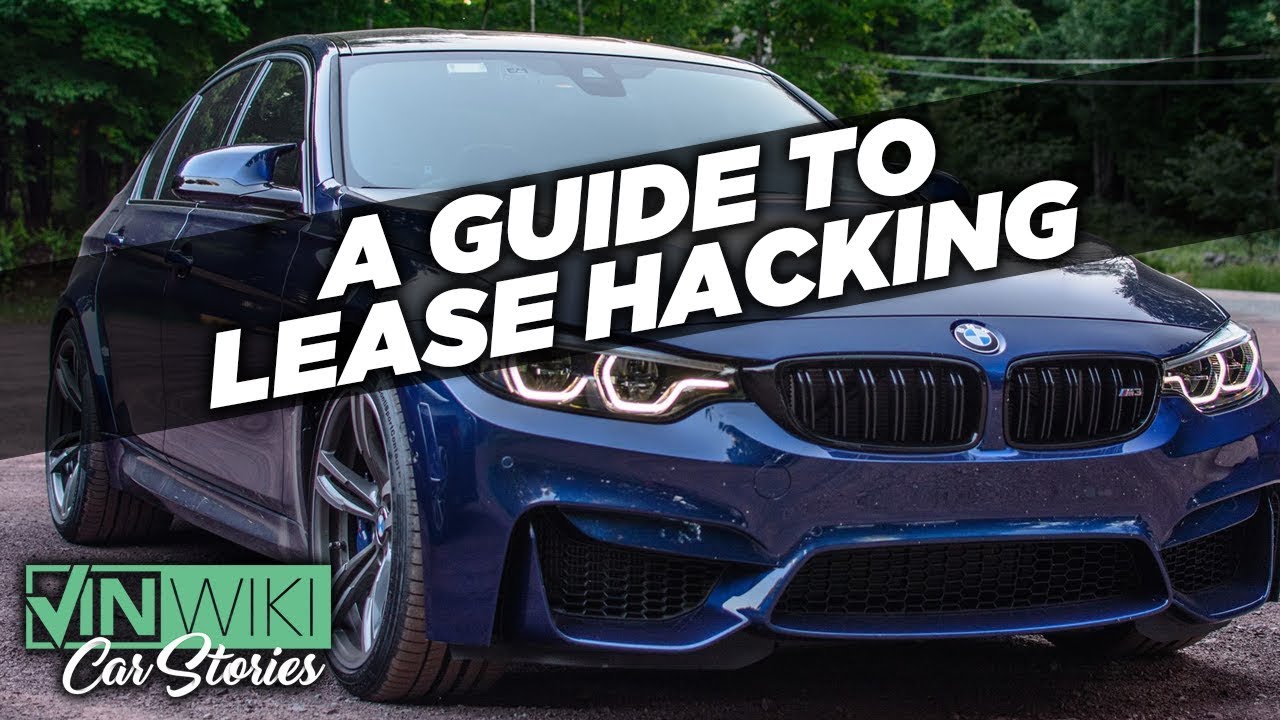
VINwiki’s automotive channel dropped a 17-minute breakdown in November 2019 called “How does luxury car lease hacking work?”, and it’s less a lifestyle video than a finance seminar dressed up as car talk. Host Scott Smith, who works with GlassParency, walks through how a small, organized group of consumers structure luxury leases to drive cars like Mercedes-Benz and BMW models for a fraction of what a typical buyer pays. The pitch isn’t a secret coupon code — it’s understanding which numbers on a lease worksheet are actually negotiable.
- Scott Smith of GlassParency hosts the 17-minute VINwiki feature explaining the mechanics of “lease hacking” luxury vehicles.
- Smith identifies capitalized cost, dealer discounts, manufacturer rebates, money factors, and residual values — not the advertised monthly payment — as the real levers to negotiate.
- The strategy targets a monthly payment near 1% of MSRP with zero money down, letting drivers cycle into a new car every two to three years while dodging F&I office markups.
Monthly Financial Metrics Are Misleading
Smith’s central warning is simple: dealerships love it when customers negotiate off the monthly payment, because that figure is the easiest one to manipulate. Stretch the term from 24 to 39 months, and the payment drops even if the total cost climbs. Lease hackers instead work backward from the capitalized cost — the negotiated price of the car — and separately attack the money factor, which functions as the interest rate baked into the lease math.
That separation matters because a dealer can quietly hold the line on cap cost while offering what looks like a friendly payment, only to have padded the money factor or shortened the residual value assumption behind the scenes. Smith walks through how residual values, which are set by the manufacturer’s captive lender rather than the dealership, can swing a deal dramatically. A vehicle with a high residual and a heavy dealer discount on the front end is the sweet spot lease hackers chase.
Reading the Incentives Like the Dealer Does
According to Smith, the real homework happens before anyone walks into a showroom. He describes cross-referencing manufacturer incentive programs — regional cash offers, lease loyalty bonuses, conquest rebates — against actual dealership inventory, then calculating what the payment should be independently rather than trusting the number printed on the dealer’s worksheet. That’s the same approach used by communities like Leasehackr, where enthusiasts build their own payment calculators to model cap cost, money factor, and residual value side by side.
Smith’s point is that manufacturers publish much of this data publicly, and a buyer who shows up already knowing the incentive stack and the correct residual percentage is negotiating from a position most salespeople aren’t used to seeing.
Lease hackers don’t chase a low monthly payment — they chase the math underneath it: cap cost, money factor, and residual value, in that order.
The F&I Office Is Where Savings Die
Even a perfectly negotiated cap cost and money factor can get eaten alive once a buyer reaches the Finance and Insurance office. Smith cautions against the marked-up add-ons pushed there — extended warranties, tire and wheel protection, and inflated acquisition fees — all of which erode the savings built earlier in the negotiation. His advice mirrors what enthusiasts discuss around vehicles like the Mercedes-Benz S-Class: the sticker experience and the finance-office experience are two entirely separate battles, and the second one is where most buyers give back everything they just won.
Chasing the 1% Benchmark
The video lands on a rule of thumb lease hackers treat as the finish line: a monthly payment near 1% of the vehicle’s total MSRP with zero down. Hit that number on a car with strong residual value and real dealer discounting, and Smith says the math works out to cycling through a new luxury vehicle every two to three years without absorbing the retail depreciation a typical owner eats. Readers chasing that same discipline elsewhere in the luxury lifestyle space will recognize the pattern — it’s the same instinct that turns any big-ticket purchase into a numbers exercise instead of an emotional one.
Smith doesn’t pretend every dealership will play along, and he’s blunt that the 1% benchmark is a target, not a guarantee — some months and some models simply won’t get there no matter how sharp the buyer’s spreadsheet is. What the video leaves viewers with is the actual order of operations: nail the cap cost, check the money factor, confirm the residual, and walk out of the F&I office before they upsell you back to square one.

Impossible Climb In Dirt Bike Graveyard
SIMPE LIFE HACKS SMART INVENTIONS
SO MUCH PROGRESS! – building a workshop in the jungle
This Fairytale Treehouse will make you Relive your Childhood Dreams
Family of 4 Travel Full Time in 4 Years | Lifestyle Changes are Hard – How You Do It Anyway